
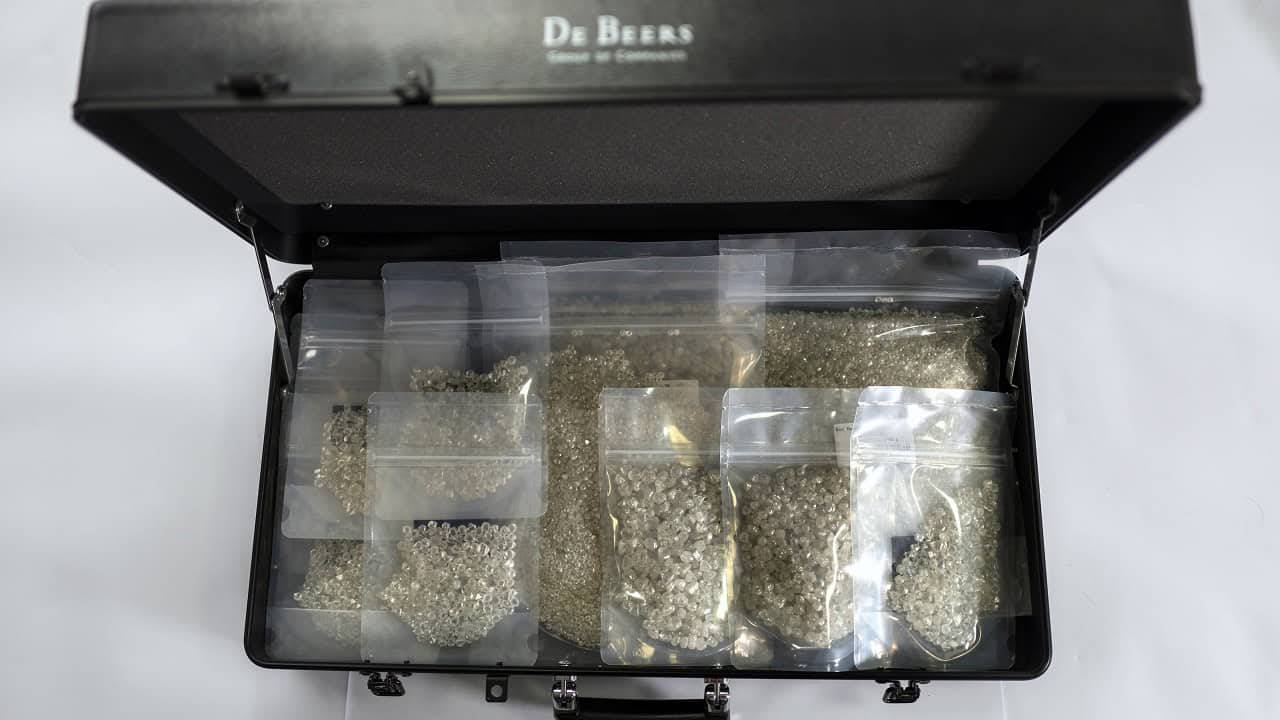
Usually, attention focuses on De Beers’ production volumes and sales value. Far less attention is paid to how it manages rough diamond inventories. It’s worth examining De Beers Q1 2026 production and sales, because it offers a clearer read on underlying demand in the diamond market.
Market Drivers
Over the past few months, Tenoris has been reporting rising demand for higher-value diamonds, driven by consumers trading up to larger natural stones. We view this shift in diamond consumer behavior as clear jewelry premiumization.
Tenoris’ panel of jewelry retailers is seeing double-digit growth in sales of larger stones, particularly in the 2-carat range and above, including 4-carat goods. Three-carat stones and mid-range 2-carat diamonds are also seeing increased demand.
A few months after this trend became visible, De Beers raised prices on larger rough in the 5–10 carat boxes, which typically yield polished stones of up to about 3.5 carats.
Given this backdrop, it’s not surprising that De Beers is prioritizing the sale, and pricing, of larger, higher-value goods. The more relevant question is what’s happening across the rest of the run of mine.
Sight 4 Deemed “Dull”
Feedback from several participants at Sight 4 (April 27–30) described the event as “dull” and “stagnant,” with many Sightholders appearing to wait for the sale of Anglo American’s 85% stake in De Beers.
What did draw attention was the presence of Garreth Penny and Nir Livnat, both of whom have assembled De Beers buying groups, in Gaborone during the Sight. They met with several Sightholders and spent time in the country, which did not go unnoticed.
Initial reports suggest the Sight was relatively small, reflecting ongoing inventory realignment across the supply chain. In part, this is due to Sightholders deferring allocations to future Sights, something De Beers has allowed without penalties, as they avoid building additional inventory in a slow market.
At the same time, there are reports of further price increases in the 5–10 carat boxes. These goods are now widely viewed as expensive, with some Sightholders voicing concerns about the mix and overall characteristics of the assortments.
All of this is unfolding against a weak trading environment, with some market participants noting that Sight goods are trading at a discount in the secondary market.
The key question remains: while demand is improving for larger, higher-quality goods, what is happening to the rest of De Beers’ production? Are inventories building, and if so, in which categories?
De Beers Q1 2026: Production vs. Sales
According to De Beers’ Q1 2026 production report, the company produced 7.133 million carats and sold 7.723 million carats, drawing 0.59 million carats from inventory.

These figures reflect total production and sales, except Gahcho Kué output, which is reported on a 51% basis.
This marks the second consecutive quarter in which sales exceeded production. A similar dynamic occurred in the fourth and second quarters of last year, when De Beers sold 2.156 and 3.416 million carats more than it produced, respectively.
Production in Q3 2025 was uncharacteristically high and temporarily broke that trend.
To be clear, some lag between production and sales is normal across all diamond producers. Goods mined in one quarter are at times sold in the next.
However, when looking at De Beers’ reported and calculated average selling prices, there appears to be a certain correlation: periods of higher sales volumes, driven by inventory drawdowns, coincide with lower average prices.

This raises a possibility: after accumulating inventory in lower-value categories, De Beers is selectively moving larger volumes at a discount to a limited number of Sightholders, on the Sight sidelines. The objective is straightforward, improving cash flow through inventory rebalancing.
Seasonality also plays a role. Factory closures around holidays, along with the need to maintain manufacturing activity and workforce utilization, can influence both rough supply dynamics and pricing.
Takeaways
Demand for very low-cost goods continues to weaken. From a consumer perspective, the comparison is increasingly direct: why purchase a low-quality natural diamond when a visually superior lab-grown alternative is available at a similar price point?
Like any company, particularly one that has recently posted a loss, De Beers is balancing multiple priorities: generating cash flow, managing inventory, and responding to shifting demand patterns. Inventory rebalancing is rarely straightforward, and current market conditions only add to the complexity.
At the same time, De Beers operates within broader constraints, including its role as a major employer in key producing countries, even as the market remains under pressure.
Looking ahead, Anglo American is expected to announce a buyer for De Beers in the not-too-distant future. When that happens, the implications could be significant, potentially reshaping not only De Beers itself, but also the broader diamond supply chain, particularly the midstream.
If you’re interested in understanding the forces shaping diamond production, pricing, and inventory realignment – including insights from De Beers’ Q1 2026 results and what they mean for your business – please get in touch.
About the Author:
